The California Fair Access to Insurance Requirements Plan was never engineered to withstand modern wildfire climatology. Conceived in 1968 through statutory amendments to address property insurance availability in urban commercial districts following the Watts riots, the mechanism operated for decades as an obscure, low-volume residual market. It provided bare-bones, named-peril property coverage—strictly limited to fire and internal explosions—acting as a temporary safety valve for properties rejected by the voluntary admitted market.
The systemic transformation of the FAIR Plan from a localized urban backstop into a quasi-primary insurer holding hundreds of thousands of residential policies and billions of dollars in exposure represents a structural failure of pricing regulation, capital adequacy, and land-use accounting. Understanding this trajectory requires a granular breakdown of how statutory constraints, adverse selection feedback loops, and catastrophic tail risk converged to break California property insurance.
The Architecture of the Residual Market
To deconstruct the failure, one must first analyze the baseline statutory design of the FAIR Plan. Unlike a state agency, it receives no direct tax appropriations. Instead, it functions as a compulsory, non-profit association pooling all property insurers licensed to operate in California. Every admitted carrier is statutorily mandated to participate, absorbing operational deficits and loss assessments proportional to their market share in the voluntary sector.
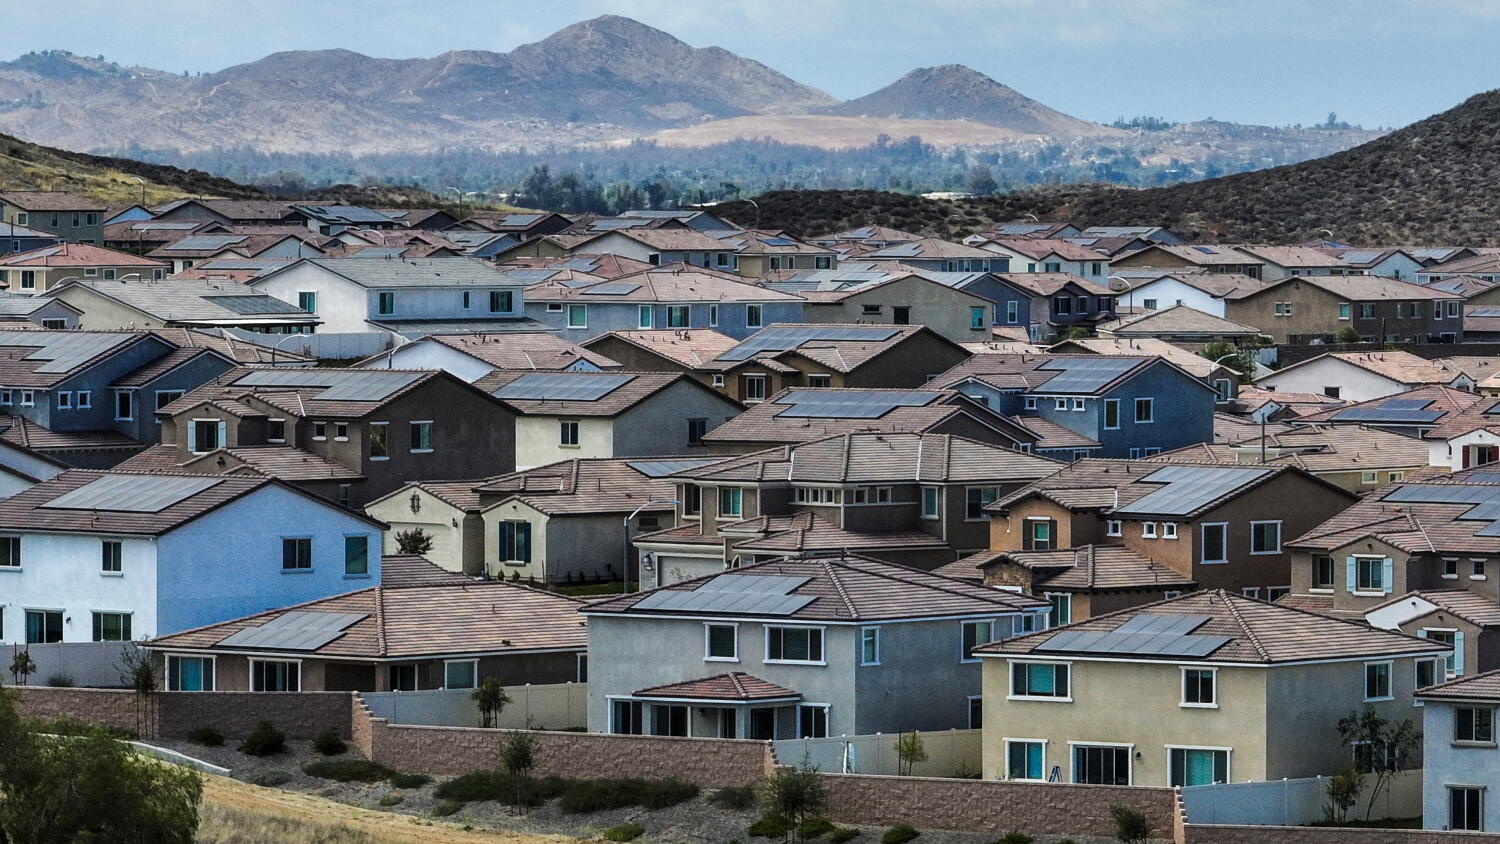
The product itself is intentionally restrictive. Historically, a standard FAIR Plan policy excludes liability, theft, and additional living expenses, requiring policyholders to purchase supplemental Difference in Conditions policies from private carriers. Yet, as private insurers retreated en masse from the Wildland-Urban Interface (WUI) due to unmodeled frequency and severity of wildfire events, the volume of properties dumped into this restricted residual pool expanded exponentially. Policy counts climbed from roughly 160,000 in 2019 to nearly 700,000 by mid-2026, representing an unprecedented migration of high-hazard properties out of private risk-bearing portfolios and into a collective liability structure.
The Mechanics of Adverse Selection and Capital Mismatch
The core economic pathology of the modern FAIR Plan stems from severe adverse selection compounded by regulatory rate suppression.
Adverse selection occurs when the pricing of an insurance pool fails to differentiate granular risk accurately, attracting participants with high probability of loss while repelling or failing to appropriately price lower risks. For decades, California’s Proposition 103 and Department of Insurance guidelines prohibited insurers from utilizing forward-looking, probabilistic catastrophe models in rate-making, forcing reliance on historical loss data. As climate-driven wildfire severity accelerated, historical baselines lost predictive validity.
Private insurers responded by freezing new policy writings or non-renewing properties in high-hazard zones to protect their balance sheets. Displaced homeowners flooded the FAIR Plan. Because the FAIR Plan's rates were statutorily suppressed or lagged far behind true actuarial risk, policyholders in high-risk zones obtained coverage at prices significantly below the expected cost of loss.
This dynamic created a profound capital mismatch:
- Exposure Accumulation: Total property exposure surged toward $700 billion.
- Reserves Depletion: Accumulated surplus and cash reserves—historically hovering around several hundred million dollars—faced immediate exhaustion following concentrated regional disaster events, such as the major Southern California fires.
- The Assessment Cascade: When claims exceed surplus, the FAIR Plan triggers cross-industry assessments, forcing solvent private carriers to pay billions to cover the deficit.
These mandatory assessments act as a tax on the voluntary market. Private insurers pass these costs downstream to policyholders throughout the state via approved surcharges. Consequently, consumers in low-risk urban centers unknowingly subsidize the structural deficits generated by insuring high-value properties in extreme wildfire zones. This triggers a self-reinforcing feedback loop: higher assessments drive more private insurers to restrict operations, which pushes more volume into the FAIR Plan, which deepens subsequent deficits.
Regulatory Realignment and Structural Limitations
Efforts to arrest this institutional decay have focused on modifying the boundary conditions between the voluntary and residual markets. Regulatory shifts allowing the integration of forward-looking catastrophe models and the partial pass-through of reinsurance costs aim to entice private capital back into the admitted market. Concurrently, legislative vehicles such as stabilization acts have sought to authorize liquidity mechanisms, bond issuances, and credit lines backed by future assessments rather than taxpayer funds.
However, these adjustments confront fundamental mathematical limits. Allowing private carriers to re-price risk or pass on reinsurance expenses inevitably results in massive short-term premium spikes for consumers. For properties situated in high-risk zones, premiums scaling to tens of thousands of dollars annually expose the underlying economic reality: certain geographic locations have become effectively uninsurable through private risk-transfer mechanisms without continuous public sector subsidy or mandatory structural hardening.
The reliance on retroactive assessments similarly strains the solvency of mid-tier domestic insurers who lack the diversified capital reserves of multinational conglomerates. If an unprecedented multi-basin fire event triggers capital calls exceeding the liquidity thresholds of participating carriers, the systemic shock threatens the integrity of the entire state property and casualty ecosystem.
Strategic Forecast
The trajectory of the residual property insurance market points away from traditional loss-pooling and toward centralized state intervention or state-backed reinsurance backstops. As long as land-use policies permit continued residential density expansion within the Wildland-Urban Interface without absolute structural mitigation mandates, the fundamental cost function remains unbroken.
Future stabilization depends entirely on enforcing strict, mandatory property-level hardening standards—such as ignition-resistant construction and defensible space perimeters—as a mandatory precondition for pool entry, paired with risk-reflective pricing that eliminates cross-subsidization. Absent these interventions, the residual market will remain a fragile fiscal mechanism perpetually vulnerable to the next localized meteorological catastrophe.