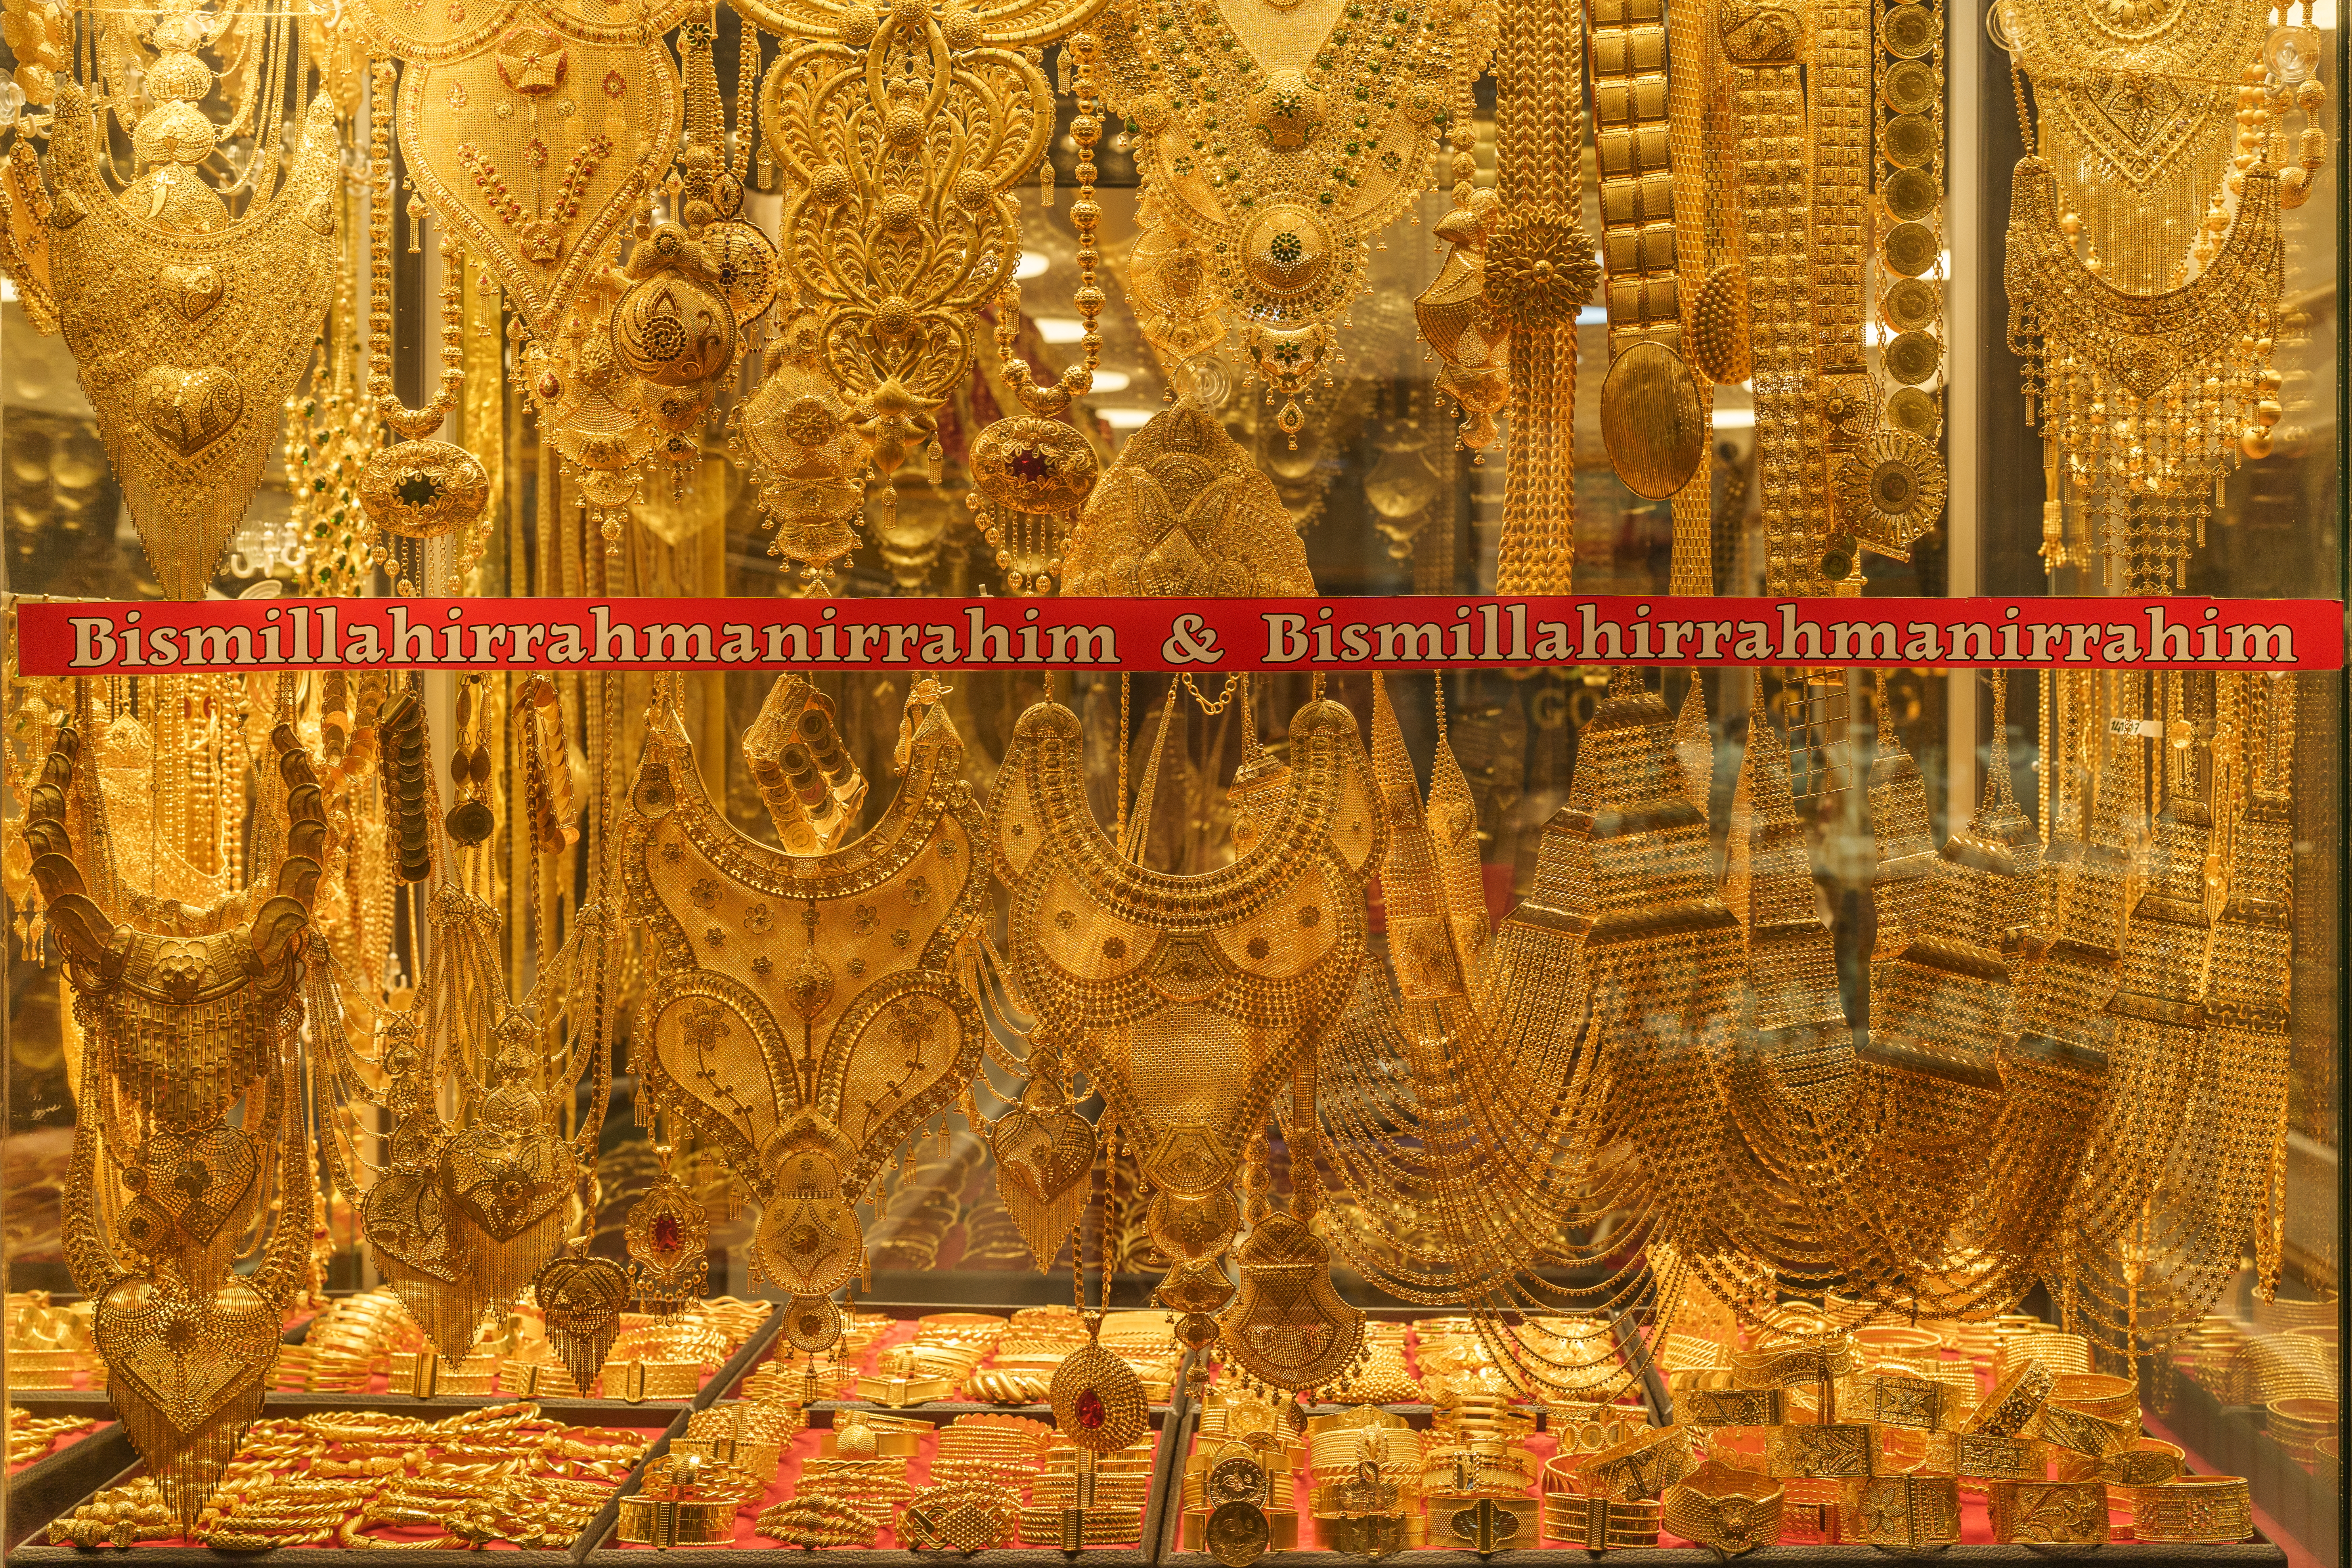
Turkish households maintain an estimated five thousand metric tons of physical gold outside the formal banking architecture, a staggering hoard valued at roughly six hundred billion dollars. To economic planners in Ankara, this massive private reserve represents capital stranded in domestic mattresses, cupboards, and safe deposit boxes. Officials frequently argue that the traditional habit of stashing gold "under the pillow" starves commercial credit markets, worsens current account deficits through persistent import pressures, and blunts the transmission of monetary policy. Yet treating this phenomenon as a mere cultural quirk misses the structural reality. Citizens are not hoarding gold out of stubborn defiance; they are engaging in rational self-preservation within a volatile macroeconomic environment.
To understand why government appeals and conversion schemes continually fall short, one must examine the mechanics of trust. Decades of chronic inflation, sharp currency devaluations, and unorthodox policy experiments have taught generations of Turkish savers a harsh lesson. Fiat currency loses purchasing power, while physical gold retains intrinsic value. When the official rate of inflation regularly climbs well into double digits, holding local currency in a commercial bank account translates to a guaranteed loss of real wealth. Gold, by contrast, operates as a parallel monetary anchor. It requires no counterparty, carries no default risk, and answers to no central bank decree. For a deeper dive into similar topics, we recommend: this related article.
The state views this idle capital through the lens of productive mobilization. If those thousands of tons of bullion entered the banking system, commercial lenders could expand credit lines to industrial enterprises, boost domestic investment, and alleviate foreign exchange constraints. Economists point out that funds locked away at home generate zero velocity. They do not circulate, they do not finance corporate expansion, and they remain entirely outside the tax net.
Yet the friction preventing this capital from entering the financial system is rooted in policy contradictions. Whenever authorities introduce gold conversion accounts or bond issuance programs designed to draw physical bullion into the treasury, participation remains muted. Savers look at past administrative measures, shifting regulatory requirements, and the persistent threat of confiscatory taxation or forced conversions. Handing over tangible, liquid gold to a banking institution in exchange for paper promises or digital yields denominated in a depreciating currency feels less like an investment and more like an expropriation. For additional information on this topic, extensive coverage can be read on Forbes.
Consider the mechanics of a typical household hedge. A middle-class family in Istanbul purchasing standard gold coins or locally crafted jewelry is not speculating on short-term market fluctuations. They are securing their children's education funds or protecting their retirement against systemic currency erosion. This behavior constitutes a vote of no confidence in the predictability of macroeconomic management. When the rules of the financial game change unpredictably, physical assets become the only reliable insurance policy available to the ordinary citizen.
Attempts to curb this informal market through heavy import quotas and restrictions on uncertified gold bars have produced unintended consequences. Rather than forcing bullion back into official channels, these constraints often widen premiums on physical gold inside the domestic market, driving transactions further into informal networks. The underlying demand does not evaporate; it simply adapts to regulatory pressure.
Blaming public behavior for macroeconomic imbalances reverses cause and effect. Capital flees into physical assets when the official monetary architecture fails to protect depositors. Until structural reforms deliver enduring price stability, institutional credibility, and positive real interest rates, citizens will continue to prioritize the absolute security of tangible wealth over the theoretical benefits of national economic mobilization. The gold beneath the pillow is not a market failure to be corrected by decree. It is a symptom of a deeper institutional deficit that no amount of government persuasion can legislate away.